ON THIS PAGE
Quick answer: Yes. North Carolina law lets insurers use credit-based insurance scores in auto and home pricing, and NC auto rates are built on ZIP-code territories. Georgia’s incoming commissioner wants to ban credit scores and ZIP codes there. A ban would shift cost between drivers rather than erase the underlying risk.
Key takeaways
- NC law allows credit-based insurance scores in auto and home pricing, with limits on how an insurer can use them against you.
- Georgia’s incoming commissioner wants to bar credit scores and ZIP codes, but a ban needs the legislature to act in 2027.
- Supporters call these factors unfair; our view is that transparency and carrier comparison are a better fix than removing pricing tools.
What we see at ALLCHOICE
This is our view as an independent agency, not a client case.
We price risk for North Carolina families every day, and our view is simple: the better the risk, the better the price should be. Credit-based insurance scores and ZIP codes are two of the tools that let carriers do that. They aren’t perfect, and we recognize the fairness concerns, especially when people have limited control over their credit history or where they live.
- Some ZIP codes simply have worse loss ratios than others.
- Statistically, better credit-based insurance scores go with fewer claims, which is why they help predict risk.
- If carriers couldn’t use these measures, we think the drivers who are the best risks, and who earn the best rates today, would see increases, while worse risks would see better rates.
- We believe removing predictive rating factors could make it harder to price risk accurately. Some carriers could face adverse selection or lower profitability and have to decide whether to keep offering that coverage. Fewer carriers means less supply, and less supply tends to push rates up.
Those outcomes aren’t guaranteed. They depend on how a law is written and how insurers respond. That is why we explain these factors to clients instead of hiding them. We show what the client can change, such as correcting errors on a credit report, and we compare carriers, because each one weighs these factors differently.
Not sure how your credit and ZIP code affect your auto rate? A Risk Advisor can compare 20+ carriers for you. Get an auto quote
How do NC insurers use credit scores and ZIP codes today?
North Carolina allows both, with guardrails. Insurers may use a credit-based insurance score in private passenger auto and home pricing, and auto base rates are set by territories defined by ZIP code.
An insurance score is built from credit report data, but it isn’t the score a lender sees. It is designed to predict claims, not repayment. The NC Department of Insurance explains that insurers using it believe better credit histories go with fewer and smaller losses.
| Factor | What it measures | How it can affect premiums |
|---|---|---|
| Credit-based insurance score | Patterns in credit history associated with insurance loss experience | Can influence the rate you are charged, subject to NC law |
| ZIP code and rating territory | Geographic differences in claim risk and loss costs | Sets the geographic part of an auto rate |
| Driving record | Accidents, convictions and related history | Can raise or lower an auto premium |
State law limits how the score can be used. Under G.S. 58-36-90:
- An insurer can’t use credit scoring as the sole basis to terminate an existing policy, meaning one in force more than 60 days.
- An insurer can use it as the sole basis for a discount.
- Insurers must file their scoring models with the Department of Insurance.
- If an adverse action involves credit, the insurer must send a notice explaining why.
- If a credit dispute proves the information was wrong, the insurer must re-rate the policy within 30 days of notice.
- If the error caused you to overpay, the insurer must refund the overpayment, calculated back to the shorter of the last 12 months of coverage or the actual policy period.
ZIP codes work differently. In the NC Rate Bureau’s Personal Auto Manual, each vehicle is assigned to a rating territory based on the ZIP code where it is principally garaged. North Carolina also limits which factors auto rates can use: classification plans may not be based on age or gender (G.S. 58-36-10).
What is Georgia’s new insurance commissioner proposing?
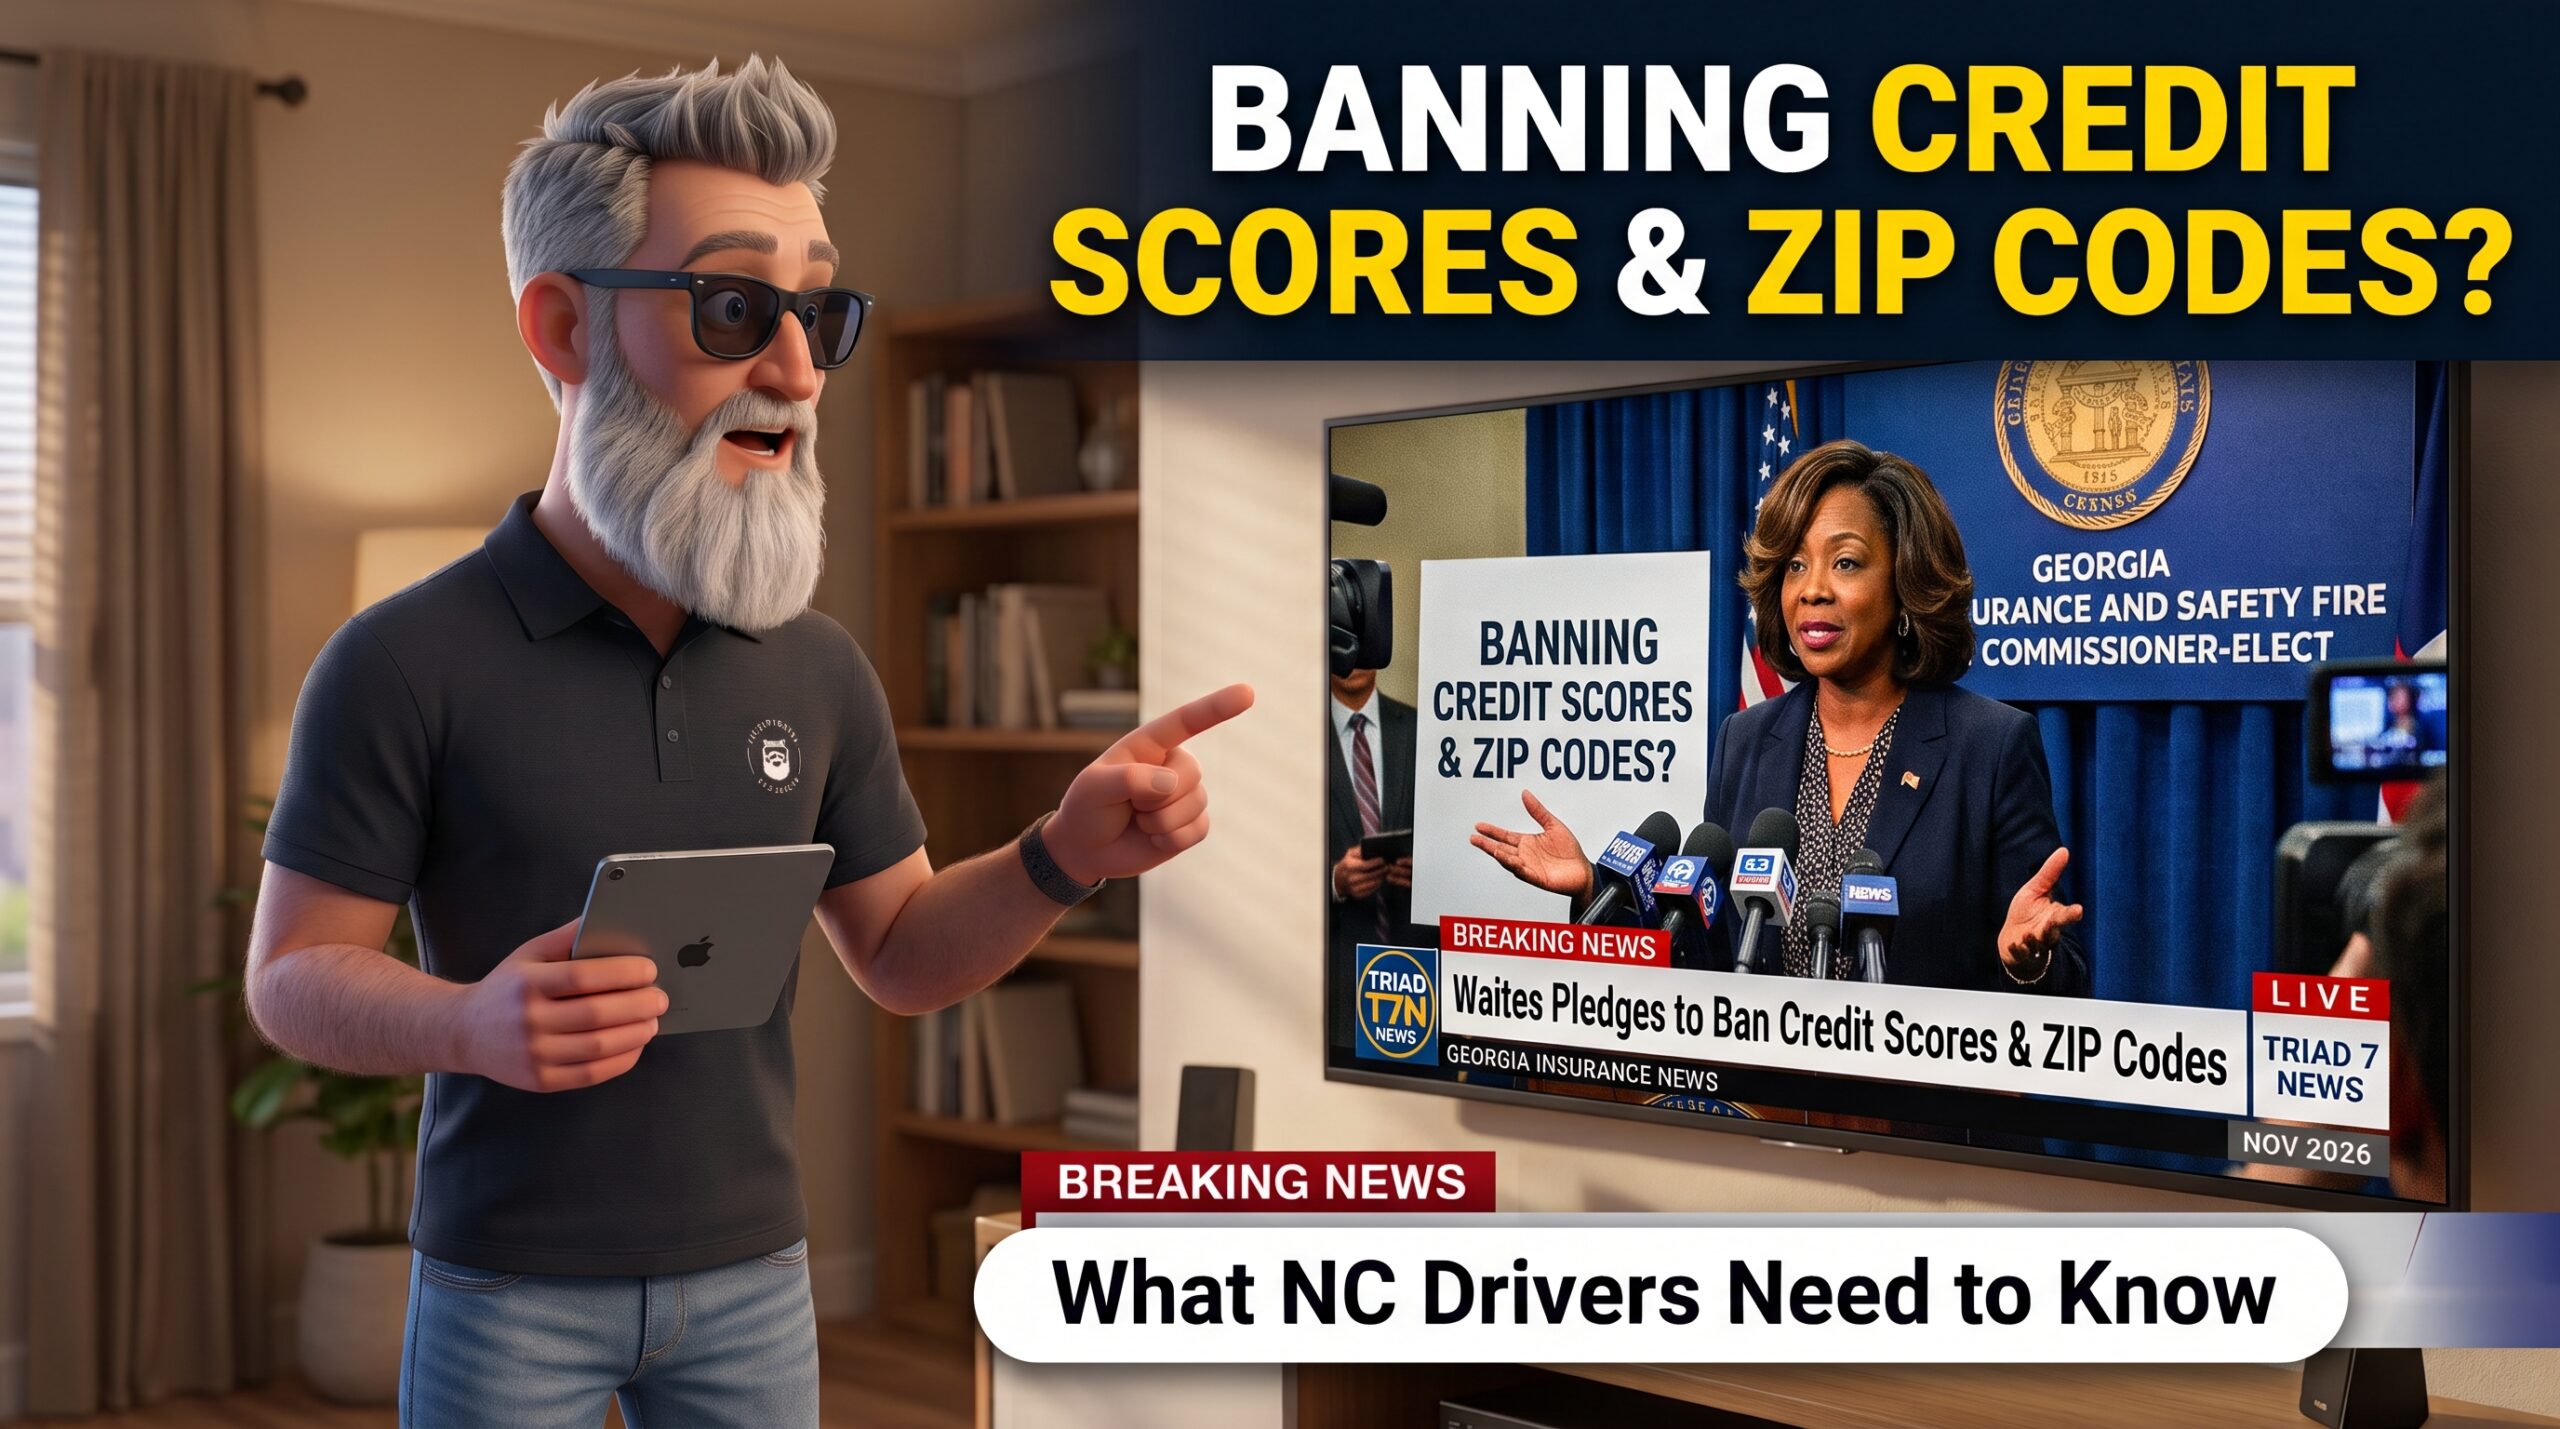
Keisha Sean Waites, who won Georgia’s insurance commissioner race on Nov. 3, has pledged to bar insurers from using ZIP codes and credit scores. She takes office in January, and a ban would need the Georgia General Assembly to pass a bill in 2027.
Insurance Journal reports she beat the incumbent 54% to 46% and also pledged to speed up claims payments and effectively freeze some auto and homeowners rates. Before the election, Grady Newsource’s candidate guide listed ending ZIP code and credit score discrimination among her priorities. After the win, she told WSB-TV that she plans to work with lawmakers on this in her first 100 days, and that she sees these factors as unrelated to risk.
The idea isn’t new in Georgia. SB 506 would bar geographic classifications such as ZIP codes in vehicle insurance, and SB 507 would bar credit scores. MoneyGeek reports SB 507 went to committee in February and never got a vote. Georgia would be the fifth state to ban credit in auto pricing; California, Hawaii, Massachusetts and Michigan already do, and Maryland, Oregon and Utah limit it.
Do credit scores and ZIP codes really predict claims?
Yes, according to the best federal research we know of, and that is the core of our concern about banning them.
The Federal Trade Commission studied credit-based insurance scores for auto insurance and reported to Congress in 2007. It found that scores effectively predict both the number of claims and their total cost, so their use makes price better match risk. On average, that means higher-risk consumers pay higher premiums and lower-risk consumers pay lower ones. That doesn’t mean someone with poor credit is a bad driver, or that credit history causes accidents. The FTC also found that scores predict claim risk within racial and ethnic groups. That study is old, and newer data may differ.
Location works the same way: claim costs differ from place to place, and NC regulators build that into rates. The NC Department of Insurance lists where you live among the factors in an auto premium, next to your driving record and vehicle.
In one Georgia quote study, MoneyGeek found poor credit added about $1,839 a year, while most ZIP codes differed by $761 or less. In MoneyGeek’s Georgia examples, differences tied to credit history were larger than most differences tied to ZIP code. The effect on any one premium depends on the insurer, location, coverage and other rating factors.
What would happen if insurers couldn’t use them?
This section is ALLCHOICE’s view, not a forecast anyone can prove. We think a ban would move cost around rather than remove it.
- Price would follow risk less closely. Today, drivers who are statistically less likely to file claims pay less. Without these factors, insurers have less information to tell them apart from higher-risk drivers.
- Rates would redistribute. MoneyGeek notes a ban would move costs among drivers. We expect many lower-risk drivers to see increases and many higher-risk drivers to see decreases.
- Insurers could face adverse selection. A loss ratio is the share of premium an insurer pays out in claims. If a carrier can’t price a group’s risk accurately, it can lose money on that group, and some carriers could see lower profitability.
- Some carriers might pull back. If a line stops being profitable in a state, carriers decide whether to keep writing it. Fewer carriers means less competition, and less competition tends to push rates up.
Georgia bills such as SB 505 would also require the commissioner to approve auto and homeowners rates before use. Combined with a ban, that would compound the pressure on carriers.
The independent-agent angle matters here. When carriers weigh these factors differently, the best protection for a driver is a Risk Advisor who shops many carriers, not fewer choices.
What do supporters of a ban say?
They say these factors penalize people for things unrelated to how they drive or care for a home, and that the effects fall unevenly by race and income.
- A LendingTree study reported by 11Alive found drivers in Georgia’s majority-Black ZIP codes pay about 11% more for car insurance on average.
- A Georgia state senator who sought the commissioner’s job called ZIP code rating modern-day redlining.
- The FTC itself found that, as a group, African-American and Hispanic consumers tend to have lower scores, so use of scores likely means they pay relatively more, even though scores predict claims within each group.
We take the fairness concern seriously. Reasonable people disagree on the remedy. Our view is that better data accuracy, clear notices, dispute rights and easy carrier comparison do more good than removing the tools that match price to risk. Supporters of a ban would answer that disparities this large justify removing the factors outright.
What this means in North Carolina
Nothing changes for NC drivers today. Credit-based scores and ZIP-code territories remain legal, filed and regulated.
But the debate isn’t only in Georgia. NC Senate Bill 979 (“Increase Insurance Rate Transparency”), filed by Sen. Murdock, would go further than today’s law without banning credit scoring outright. For private passenger auto and residential property insurance, it would bar insurers from using credit scoring as any basis to terminate an existing policy or coverage, or to put a policy under rate-deviation consent. Insurers could still use credit as the sole basis for a discount. It would apply to policies issued, amended or renewed on or after October 1, 2027. In the version we reviewed, the bill was re-referred to the Senate Appropriations/Base Budget Committee on May 5, 2026.
Triad
Auto territories follow ZIP codes, and a single city can span more than one. News coverage of Rate Bureau filings describes Greensboro ZIP codes split between territories 340 and 350.
Mountains and coast
For home insurance, location also drives wind, hail and flood exposure, so a Wilmington or Asheville home can be priced very differently from a Greensboro one for reasons that have nothing to do with credit.
What you can do now
- Request your credit reports from Equifax, Experian and TransUnion, and dispute errors.
- Ask your insurer which parts of your credit history hurt your insurance score most; NCDOI says the insurer should be able to tell you.
- Avoid applying for several new credit accounts in a short window.
- If a dispute corrects an error, ask for a re-rate; the 30-day rule in G.S. 58-36-90 applies once the insurer is notified.
- Compare carriers. Consumer Reports found how credit figures into premiums varies by insurer.
Questions to ask your Risk Advisor
- Which of the carriers you quoted weigh credit most heavily for my situation?
- Which rating territory is my ZIP code in, and did it raise my base rate?
- If I fix an error on my credit report, how fast can you ask for a re-rate?
People also ask
Yes. North Carolina allows insurers to use a credit-based insurance score in auto and home pricing. Insurers must file their scoring models with the NC Department of Insurance.
Not on credit alone. Under G.S. 58-36-90, an insurer can’t use credit scoring as the sole basis to terminate a policy that has been in force more than 60 days. It can use credit as the sole basis for a discount.
Yes. NC auto rates use rating territories made of ZIP codes. Your vehicle is assigned by the ZIP code where it is principally garaged, so two drivers with the same record in different territories can pay different base rates.
Not necessarily. Prohibiting a rating factor doesn’t reduce the total cost of claims, so premiums mostly shift between drivers. Whether yours goes up or down depends on your risk profile, your carrier and the other factors in your rate.
Not yet. Georgia’s incoming commissioner has pledged to push for a ban, but it would take a bill passed by the General Assembly, and the earliest chance is 2027.
Final Verdict
Credit scores and ZIP codes are legal, regulated pricing tools in North Carolina, and they help match price to the risk each driver brings. Banning them would not remove that risk; we expect it would move cost between drivers and could thin out carrier competition. For most NC drivers, the practical move is to understand your score, fix errors, and have a Risk Advisor shop multiple carriers.
Ready to see how carriers price you? Get an auto quote or call 844.540.0463.
Current clients: visit the Member Center.
Related reading: Auto insurance in NC · Home insurance in NC · What Is the NC Safe Driver Incentive Plan? · Uninsured vs. Underinsured Motorist Coverage in NC
Coverage depends on your policy, carrier and situation. This article is general information, not a coverage decision — talk to your Risk Advisor about your policy.
Sources
- Grady Newsource: Georgia Insurance & Safety Fire Commissioner candidate guide (Oct. 8, 2026)
- Insurance Journal: Waites defeats King (Nov. 4, 2026)
- WSB-TV: Commissioner-elect lays out plan
- MoneyGeek: Georgia commissioner and credit scores (Nov. 6, 2026)
- 11Alive: Georgia majority-Black ZIP codes and car insurance
- Capital B Atlanta: ZIP code rating and credit score bills
- FTC: Report on credit-based insurance scores (July 24, 2007)
- NC Department of Insurance: Insurance credit scoring in NC
- N.C.G.S. 58-36-90
- N.C.G.S. 58-36-10
- NC Senate Bill 979 (2025 session, version 1)
- BillTrack50: NC S979 status and committee history
- NC Rate Bureau: Personal Auto territory rule (circular A-15-3)
- InsuranceNewsNet: Triad auto rate requests by territory
- WRAL: Consumer Reports on credit and premiums
- ValuePenguin: Credit and auto insurance rates